Savings Calculator

Project your future balance, interest earned, and wealth growth with compound interest.

Last updated:
Year Deposit Interest Ending Balance

Was this calculator helpful?

★ ★ ★ ★ ★

Calculation Examples

Calculation Case Result
$5,000 initial deposit + $100/month at 5%, 5 years, monthly compounding Projected balance of about $13,217 (interest about $2,217)
$10,000 for 10 years at 5%: daily vs. monthly compounding Daily compounding earns about $17 more in total
$10,000 for 10 years: 4.5% vs. 0.38% annual rate About $15,530 versus $10,387
Growing $10,000 to $1,000,000 at 7% annual return Takes approximately 68 years without additional contributions
Mihail Doncenco
Mihail Doncenco Site Creator & Calculator Expert

Founder and developer of CalcMate. Builds and maintains every calculator on this site, focusing on formula accuracy and clear, practical results.

How to Use the Savings Calculator

Start by entering your initial deposit in the Principal field. Then enter the annual interest rate your bank pays. Select the Compounding Frequency, which sets how often earned interest is added to your balance (daily, monthly, quarterly, or annually).

For ongoing contributions, enter your monthly deposit and choose whether it lands at the beginning or end of each period. Click the calculate button to see your projected future value, total interest earned, and a split between your own deposits and compound growth. It suits an emergency fund, a down payment, or any long-term savings goal. Results are projections at a fixed rate, not guarantees and not financial advice.

How Savings Interest Calculations Work

Compound interest pays interest on earlier interest, while simple interest pays only on your original principal. The calculator uses the standard formula \(A = P(1 + r/n)^{nt}\), where \(A\) is the final balance, \(P\) is the principal, \(r\) is the annual rate as a decimal, \(n\) is the number of compounding periods per year, and \(t\) is the time in years. For regular deposits, it adds the future value of an annuity.

Worked example: $5,000 at 5% with $100 added at the end of each month, compounded monthly, grows to about $13,217 after 5 years. The principal grows to $6,417 and the deposits to $6,801. You deposit $11,000 in total, so interest is about $2,217. Compounding frequency changes the effective yield: 5% compounded annually yields 5.000%, monthly 5.116%, and daily 5.127%. On $10,000 over 10 years, daily compounding earns only about $17 more than monthly. For a quick estimate of doubling time, divide 72 by the rate in percent: at 4%, money doubles in about 18 years.
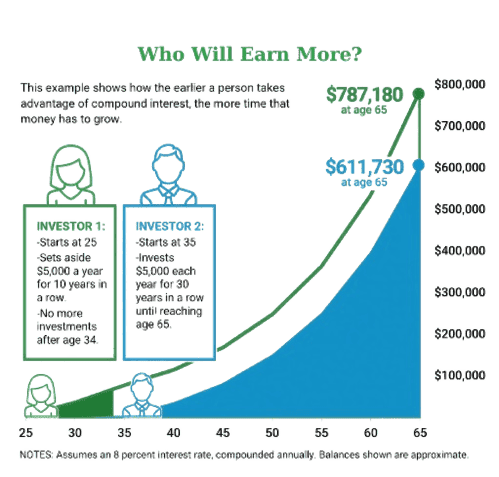
Compound interest comparison: who earns more with monthly vs annual compounding

Useful Tips 💡

  • Recheck your rate every quarter. Savings rates follow Federal Reserve policy, banks change them without notice, and some top rates are promotional and drop after a set period.
  • Subtract inflation to see real growth. A 4.5% rate with 3% inflation gives a real return of about 1.5% (exactly 1.46%).
  • Check deposit insurance. FDIC coverage is $250,000 per depositor, per bank, per ownership category, so split larger balances across banks or categories.

📋Steps to Calculate

  1. Enter your starting principal amount and current annual interest rate.

  2. Set the time period and select your compounding frequency (daily, monthly, quarterly, or annually).

  3. Click Calculate to see your projected balance, total interest, and contribution breakdown.

Mistakes to Avoid ⚠️

  1. Using simple interest instead of compound interest. At 5% for 20 years on $10,000, simple interest gives $20,000, while annual compounding gives $26,533.
  2. Selecting the wrong compounding frequency. At 5% for 20 years on $10,000, annual compounding gives $26,533 and monthly compounding gives $27,126, a difference of $593.
  3. Ignoring inflation. A nominal 5% rate with 3% inflation leaves a real return of only about 1.9%.
  4. Mixing up deposit timing. Beginning-of-period deposits earn one extra period of interest. On $100 a month at 5% for 5 years, that adds about $28 ($6,829 versus $6,801).

Practical Applications📊

  1. Build an emergency fund: $400 a month for 12 months at 4% compounded monthly reaches about $4,889, which is $4,800 deposited plus about $89 in interest.

  2. Compare accounts: $10,000 for 10 years at 4.5% compounded annually grows to about $15,530, but at the 0.38% national average rate (FDIC, August 2026) it grows to only about $10,387.

  3. Plan long-term goals: $500 a month for 30 years at a constant 7% adds up to about $610,000 on $180,000 of deposits. Real returns vary from year to year, so treat this as a scenario.

Questions and Answers

Can I use the savings tool for monthly projections and short-term goals?

Yes, set the time horizon to 6 or 12 months and add a monthly contribution to see your balance build up. To reach a $3,000 down payment in 12 months at 4% compounded monthly, you need to deposit about $245 a month at the end of each month. Seeing the monthly target turns a vague goal into a specific amount, and you can adjust the deposit or timeline until the plan fits your budget.

How does a savings interest calculator account for compound growth?

The calculator applies \(A = P(1 + r/n)^{nt}\) to your initial deposit and adds the future value of an annuity for recurring contributions. Compounding frequency matters because more frequent compounding gives a higher effective yield on the same nominal rate. A 5% nominal rate yields 5.000% compounded annually, 5.116% monthly, and 5.127% daily. The gap between daily and monthly is small: on $10,000 over 10 years it is about $17. The gap between annual and monthly is larger: on $10,000 over 20 years it is $593.

What is a savings calculator?

A savings calculator is a planning tool that projects your account balance from your starting deposit, interest rate, compounding frequency, and regular contributions. It shows your future balance, total interest earned, and how much of the growth came from your deposits versus compounding. People use it for short goals such as a vacation fund and long ones such as retirement savings. It is most useful for comparing accounts: a 4 percentage point rate gap on $10,000 compounds into thousands of dollars over a decade.

What makes a High-Yield Savings Account (HYSA) better for long-term growth?

A high-yield savings account pays a much higher rate than a typical bank savings account, with the same FDIC insurance of up to $250,000 per depositor, per bank, per ownership category. The FDIC national average savings rate was 0.38% in August 2026, while leading online accounts advertised up to 5.00% APY in early October 2026, although some top offers apply only to new customers for the first 6 months (Motley Fool rate table, October 4, 2026). On $10,000 over 10 years, 4.5% instead of 0.38% (both compounded annually) earns about $5,100 more in interest. Rates are variable, so rerun the calculator with the current rate before you choose an account.

What mathematical formulas power the Savings Calculator?

The calculator combines two standard formulas from financial mathematics. For the initial deposit: \(A = P(1 + r/n)^{nt}\), where \(P\) is the principal, \(r\) is the annual rate (decimal), \(n\) is compounding periods per year, and \(t\) is time in years. For recurring contributions, it uses the future value of an ordinary annuity: \(FV = PMT \times \frac{(1 + r/n)^{nt} - 1}{r/n}\), where \(PMT\) is the payment per period. For deposits at the start of each period, multiply that result by \(1 + r/n\). The two results are added to get the projected balance. The annuity formula assumes deposits and compounding happen at the same frequency, such as monthly deposits with monthly compounding.

What role does an APY calculator play in realistic financial planning?

APY (Annual Percentage Yield) is the interest you actually earn in one year including compounding, so it is more accurate than the nominal rate: \(\text{APY} = (1 + r/n)^n - 1\). For example, a 5% nominal rate compounded monthly has an APY of 5.116%, not 5.00%. Two accounts both advertising 5% can pay different amounts if they compound differently. Banks must disclose APY under Regulation DD (12 CFR Part 1030), which implements the Truth in Savings Act. If you enter the nominal rate and pick a compounding frequency, the calculator builds the APY itself. If you only have the APY, choose annual compounding so compounding is not counted twice.
Disclaimer: This calculator is designed to provide helpful estimates for informational purposes. While we strive for accuracy, financial (or medical) results can vary based on local laws and individual circumstances. We recommend consulting with a professional advisor for critical decisions.