Expense Ratio Calculator

See how much fund fees cost you in dollars over your investment horizon, and how much more your portfolio would be worth without them.

Last updated:
Future value after expenses:
Total cost due to expense ratio:
Calculation breakdown with your numbers
1. Net return rate = % − % = %
2. Future value with expenses (what you actually get): Starting with + adding each year growing at % per year for years →
3. Future value if there was 0% expense ratio: Same amounts, but growing at full % per year →
4. Cost of the expense ratio over years = − =

Was this calculator helpful?

★ ★ ★ ★ ★
Embed this calculator

Calculation Examples

Calculation Case Result
Index fund: $10,000 initial, $5,000/yr, 20 years, 7% gross return, 0.05% expense ratio Fee impact approx. $1,500 (final balance approx. $242,200 instead of $243,700)
Active fund: $10,000 initial, $5,000/yr, 20 years, 7% gross return, 0.85% expense ratio Fee impact approx. $23,800 (final balance approx. $219,900)
High-fee scenario: $50,000 lump sum, 30 years, 8% gross return, 1.20% expense ratio Wealth lost to fees approx. $143,300 (final balance approx. $359,800 instead of $503,100)
Mihail Doncenco
Mihail Doncenco Site Creator & Calculator Expert

Founder and developer of CalcMate. Builds and maintains every calculator on this site, focusing on formula accuracy and clear, practical results.

How to Use the Expense Ratio Calculator

Enter your starting investment and any planned annual contribution. Then enter the expected gross annual return, the number of years you will stay invested, and the fund's annual expense ratio, which you can find in the fee table at the front of its prospectus or on its fact sheet.

The calculator runs two projections: one at the gross return (no fees) and one at the net return after the expense ratio. The gap between the two final balances is the total wealth lost to fees. It includes the fees you paid and the growth those fees would have earned had they stayed invested. That second part is why a small expense ratio becomes large over decades.

Use the net expense ratio, not the gross one, because the net figure reflects fee waivers and contractual caps that lower what you actually pay. The tool assumes a constant return, contributions at the end of each year, no taxes, and nominal dollars. It is an estimate, not a forecast or investment advice, since real returns vary every year.

The Mathematics of Fee Erosion

The calculator approximates the net return as: \[r_{net} = r_{gross} - \text{Expense Ratio}\] It then applies the future value formula for a lump sum plus yearly contributions: \[FV = PV(1 + r)^n + PMT \times \frac{(1 + r)^n - 1}{r}\] where \(PV\) is the initial investment, \(PMT\) is the annual contribution, \(r\) is the annual return (gross or net), and \(n\) is the number of years.

Running the formula twice, at \(r_{gross}\) and at \(r_{net}\), isolates the cumulative fee cost. The result is not intuitive, because each dollar paid in fees also loses all its future growth. Take a $50,000 lump sum for 30 years at a 7% gross return. With no fee it grows to about $380,600. With a 1% expense ratio it grows to about $287,200, so the fee costs about $93,400, or roughly 24.5% of the final balance, even though the stated fee is 1% a year.
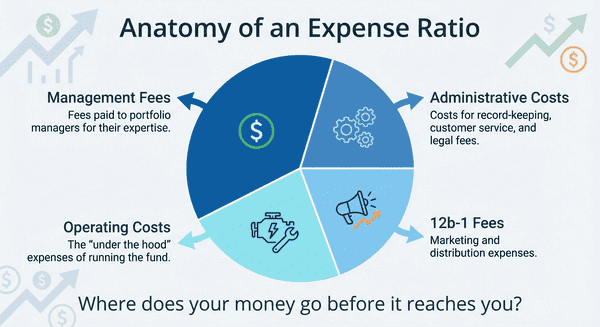
Anatomy of an expense ratio diagram showing fee deduction from gross return and compounding impact over time

Useful Tips 💡

  • Use the net expense ratio from the prospectus, not the gross one, but check when any fee waiver expires, since the cost can rise afterward.
  • Run a conservative case with a lower gross return, such as 4% instead of 7%, to see that fees take a larger share of gains when markets grow slowly.

📋Steps to Calculate

  1. Enter your initial investment and planned annual contributions.

  2. Set the investment horizon in years and the expected gross annual return percentage.

  3. Enter the fund's net expense ratio and click Calculate to see the fee impact in dollars.

Mistakes to Avoid ⚠️

  1. Looking only at the percentage and skipping the dollar impact: a 1% fee looks small, but over 30 years it can take about a quarter of the final balance.
  2. Ignoring trading commissions, bid-ask spreads, and sales loads, which are separate from the annual expense ratio and add to total cost.
  3. Assuming fees stay flat in dollars: they are charged on a growing balance, so the yearly dollar cost rises as the portfolio grows.
  4. Reading the results as inflation-adjusted: they are nominal, so real purchasing power will be lower.

Practical Applications📊

  1. Compare a low-cost index ETF at 0.03% with an actively managed fund at 0.75% on the same capital and return assumptions, and see the dollar gap.

  2. Check a 401(k) menu: if two funds track similar markets but one charges 0.05% and another 0.90%, the calculator shows the lifetime cost of choosing the second.

  3. Weigh switching from an old high-fee fund to a cheaper one, remembering that selling may trigger taxes or fees that you must count against the savings.

Questions and Answers

Does the expense ratio include brokerage commissions?

No, the expense ratio covers only the fund's internal running costs. It leaves out the commission you pay your broker, the bid-ask spread on ETF trades, front-end or back-end sales loads on mutual funds, and the trading costs the fund pays when it buys and sells securities. Those internal trading costs can be large for funds with high portfolio turnover, and they appear in returns, not in the stated expense ratio.

How does the expense ratio affect 401(k) returns over a career?

A 1 percentage point higher fee reduces a 30-year 401(k) balance by roughly a quarter. On $200,000 growing at a 7% gross return, a fund charging 1% ends at about $1.15 million, while a no-fee fund ends at about $1.52 million, a gap of about $374,000. Most plans offer a limited menu, so check the fees in your plan. In the United States, plan sponsors must give participants fee disclosures each year under the Department of Labor's ERISA section 404(a)-5 rule. Also weigh any employer match, which can outweigh the fee difference.

How is the expense ratio calculated by the fund?

The fund divides its total annual operating expenses by its average net assets for the year. A fund with $1 billion in average assets and $5 million in annual expenses has an expense ratio of 0.5%. The ratio appears in the fee table of the fund's prospectus (Form N-1A in the United States) and on its website, and it is updated at least once a year. It does not include trading costs inside the portfolio.

What is a good expense ratio for an ETF or index fund?

For a broad-market index ETF, such as one tracking the S&P 500 or total US market, a competitive expense ratio in 2026 is below 0.10%. Major providers offer funds at around 0.03%, and some index funds from Fidelity charge 0.00%, but check each fund's current fee, since providers change them. Actively managed equity funds usually charge 0.50% to 1.20%. S&P's SPIVA scorecards have repeatedly found that most active US large-cap funds lag the S&P 500 over 10 and 15 years, and Morningstar research has found expense ratios to be among the better predictors of future fund performance.

What is an expense ratio in simple terms?

An expense ratio is the yearly fee a fund charges, as a percentage of your invested assets, to cover its operating costs. These costs include portfolio management, administration, and sometimes marketing (12b-1) fees. A 1% expense ratio on $10,000 costs $100 in the first year, and more later as the balance grows. You never receive a bill: the fee comes out of the fund's assets each day, so it lowers the net asset value (NAV) per share instead of showing as a line on your statement.

What is the difference between gross and net expense ratio?

The gross expense ratio is the fund's total operating cost before any waivers, and the net expense ratio is what investors pay after the fund company waives or caps part of its fees. Waivers are often contractual for a set period, usually to keep a new or small fund competitive, and they can expire, after which the ratio moves back toward the gross figure. Use the net ratio for your calculation, and check the prospectus for the waiver end date, because your long-term cost may be higher than the current net ratio.

Why should I use an expense ratio calculator?

Fees are taken from the fund's assets quietly, so their cumulative cost is hard to see day to day. Most investors know their expense ratio as a percentage but have never seen it as a dollar amount over their horizon. The calculator shows it: on $10,000 plus $5,000 a year for 20 years at a 7% gross return, a 0.85% fund ends about $22,300 below a 0.05% fund. FINRA's Fund Analyzer and similar tools from regulators also help with comparing fund costs before you invest.
Disclaimer: This calculator is designed to provide helpful estimates for informational purposes. While we strive for accuracy, financial (or medical) results can vary based on local laws and individual circumstances. We recommend consulting with a professional advisor for critical decisions.
