Credit Card Payoff Calculator

Find out how long it takes to pay off your credit card balance and how much interest you will pay in total.

Last updated:

Was this calculator helpful?

★ ★ ★ ★ ★
Embed this calculator

Calculation Examples

Calculation Case Result
$5,000 balance, 22% APR, $150 per month Paid off in 52 months (4.3 years), about $2,800 in total interest
Minimum payment only (1% plus interest) on $5,000 at 20% APR About 19 years and about $7,300 in interest
$3,000 balance at 19% APR: $100 vs $150 per month 42 months and $1,102 in interest vs 25 months and $636 in interest
Add $50 to $150 per month on $5,000 at 22% APR About 18 months faster and about $1,000 less interest
Mihail Doncenco
Mihail Doncenco Site Creator & Calculator Expert

Founder and developer of CalcMate. Builds and maintains every calculator on this site, focusing on formula accuracy and clear, practical results.

How to Use the Credit Card Payoff Calculator

Have your latest credit card statement ready. Enter your Current Balance, your Annual Percentage Rate (APR), and your planned Monthly Payment. You can model minimum payments only or any fixed amount you choose.

The calculator shows how many months it takes to reach a zero balance and your total interest cost. Try adding $50 to your payment. On a $5,000 balance at 22% APR, going from $150 to $200 a month cuts payoff from 52 months to about 34 months and saves roughly $1,000 in interest. Results are estimates, not financial advice.

How Credit Card Payoff Calculations Work

The calculator builds a revolving-debt amortization schedule. Each month, interest equals your balance times the periodic rate \(r = \text{APR} / 12\). Your payment covers interest first, and the rest reduces the principal. As the principal falls, interest falls too, so more of each payment goes to the balance. Your payment must exceed the monthly interest \(P \times r\), or the balance never shrinks: at 22% APR on $5,000, that interest is $91.67.

For a fixed payment \(M\), the number of months is \(n = -\ln(1 - Pr/M) / \ln(1 + r)\). Real issuers use the average daily balance and a daily periodic rate of about APR/365. With daily compounding, a 20% APR costs about 22.1% a year, so a statement can differ from this monthly estimate by a few dollars. The Federal Reserve G.19 release (October 7, 2026) put the average rate at 22.15% for accounts assessed interest and 20.94% for all accounts in Q2 2026. If you pay the full statement balance each month, you normally owe no interest on new purchases.
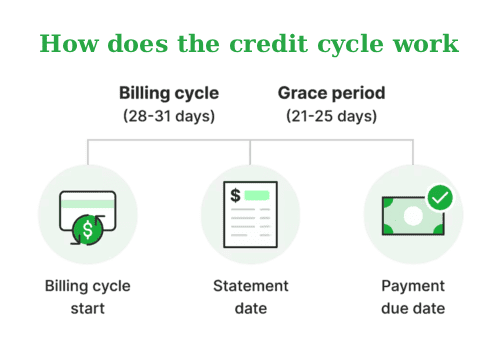
Credit card payoff cycle diagram showing how payments reduce principal over time

Useful Tips 💡

  • With several cards, pay extra toward the highest-APR balance first. This is the debt avalanche method, and it minimizes total interest. For example, with $2,000 at 24% and $3,000 at 15%, the 24% card comes first.
  • Check your statement each month and update the balance in the calculator to keep projections accurate.
  • Pay the full statement balance whenever you can. Under the Credit CARD Act of 2009, issuers must mail statements at least 21 days before the due date, and paying in full normally avoids interest on new purchases.

📋Steps to Calculate

  1. Enter your current balance, APR, and the monthly payment amount you can commit to.

  2. Choose minimum payment only or set a custom fixed amount.

  3. Review the full repayment timeline and total interest projection.

Mistakes to Avoid ⚠️

  1. Paying only the minimum. On $5,000 at 20% APR with a minimum of 1% of the balance plus interest, payoff takes about 19 years and interest totals about $7,300, more than the original balance.
  2. Overlooking balance transfer fees (typically 3 to 5%) and the date the promotional APR expires. A 3% fee on $5,000 is $150; 5% is $250.
  3. Making new purchases while paying the card down. A card carrying a balance usually has no grace period, so new purchases start accruing interest and push the payoff date out.
  4. Assuming interest is charged once a month. Most issuers use the average daily balance, so this monthly estimate can differ from your statement by a few dollars.

Practical Applications📊

  1. Test extra payments. On a $5,000 balance at 22% APR, $200 a month instead of $150 shortens payoff by about 18 months and saves roughly $1,000 in interest.

  2. Compare debt avalanche (highest APR first) with debt snowball (smallest balance first) across several cards.

  3. Work backward from a payoff date. To clear $5,000 at 20% APR in 24 months, you need about $255 a month.

Questions and Answers

Can I use this calculator to plan strategies for multiple credit cards?

Yes, enter each card separately and compare the Debt Avalanche (highest APR first) with the Debt Snowball (smallest balance first). The avalanche always minimizes total interest. The snowball gives earlier wins: Gal and McShane (Journal of Marketing Research, 2012) found that closing accounts early in a debt management program predicted whether people eliminated their debt. The cost difference between the two is often modest, so pick the one you will stick with.

How does a payoff tool differ from a standard debt calculator?

A payoff calculator models the repayment timeline and the effect of extra payments, while a standard debt calculator only totals what you owe. On $3,000 at 19% APR, raising the payment from $100 to $150 a month shortens payoff from 42 months to 25 months and cuts interest from $1,102 to $636, a saving of $466. That time-to-zero view turns a debt figure into a plan you can follow.

Is a credit card amortization schedule useful for long-term planning?

Yes, an amortization schedule splits each payment into interest and principal, month by month. On $6,000 at 16% APR with a payment of $202.29, payoff takes 38 months and total interest is about $1,688. In month 1, $80 of the payment is interest (40%) and $122 reduces the principal; by the last months nearly all of it is principal. The Credit CARD Act of 2009 also requires card statements to show how long minimum payments would take to pay off the balance and the payment needed to clear it in 36 months.

What formula does the calculator use to compute the payoff schedule?

The calculator uses the standard loan amortization formula: \[M = \frac{P \cdot r \cdot (1 + r)^n}{(1 + r)^n - 1}\] where \(P\) is the outstanding principal, \(r\) is the monthly periodic rate \((\text{APR} / 12)\), and \(n\) is the number of months. Solving for the number of months at a fixed payment gives \(n = -\ln(1 - Pr/M) / \ln(1 + r)\), which works only when \(M > Pr\). For $5,000 at 22% APR with $150 a month, \(r \approx 0.018333\) and \(n \approx 52\) months.

What is a credit card payoff calculator and how does it reduce debt?

A credit card payoff calculator shows how many months it takes to clear a balance and how much interest you pay, given your APR and monthly payment. For example, a $5,000 balance at 20% APR with a minimum of 1% plus interest takes about 19 years and costs about $7,300 in interest, while a fixed $250 a month clears it in 25 months with about $1,133 in interest. The Federal Reserve reported an average rate of 22.15% on accounts assessed interest in Q2 2026, so interest is the main cost of carrying a balance. Seeing both timelines side by side makes a larger payment easier to commit to.
Disclaimer: This calculator is designed to provide helpful estimates for informational purposes. While we strive for accuracy, financial (or medical) results can vary based on local laws and individual circumstances. We recommend consulting with a professional advisor for critical decisions.
